


Note from Gaetano: This is a guest post by Ayomide Joseph. I have personally reviewed and edited it for accuracy and legitimacy. I stand by the arguments made in this guest post.
I ran 270 query variations across ChatGPT, Gemini, and Perplexity, asking each one for “alternatives to” three specific B2B SaaS products.
Specifically looked at:
Alternatives to Kustomer
Alternatives to Okta
Alternatives to LinearB
I tested 30+ different phrasings per product, across three LLMs, single-shot captures in fresh chats. The kind of range an actual B2B SaaS buyer would encounter during a real evaluation cycle.
The full report is available at the end of this post, but the main takeaways are summarized below.
There’s just way too much noise right now.
Marketers are glorifying GEO tactics, but fail to understand why posts that “go viral” on LinkedIn are promoting ideas that generate the lowest ROI.
GEO agencies are pitching baseless “AI search readiness” audits as a sales technique to generate leads.
GEO vendors are buying brand mentions on spam sites and framing it as a credible way to grow your brand mention/citation rate.
Meanwhile, the data argues that AI visibility is a category positioning problem operating on a timeline compression that most B2B marketing plans have not accounted for.
Here are three mistakes I think B2B marketing leaders are making right now, and what the data suggests they should do instead.
Mistake 1: Treating AI search like an SEO ranking problem when it’s really a category eligibility problem
AI search does not behave like a traditional SEO ranking system. It behaves like a category inclusion/exclusion filtering system.
Marketers are treating AI search like it’s something you need to optimize for, when it’s really something you need to qualify for:
Kustomer Alternatives: four brands appeared in the top five of almost every response: Zendesk, Gorgias, Freshdesk, and Intercom. The fifth-most-frequent brand appeared less than half as often.
Okta Alternatives: five brands owned the pool: Microsoft Entra ID, JumpCloud, OneLogin, Ping Identity, Auth0.
LinearB Alternatives: the same shape is held with Swarmia, Jellyfish, Waydev, Haystack, DX.
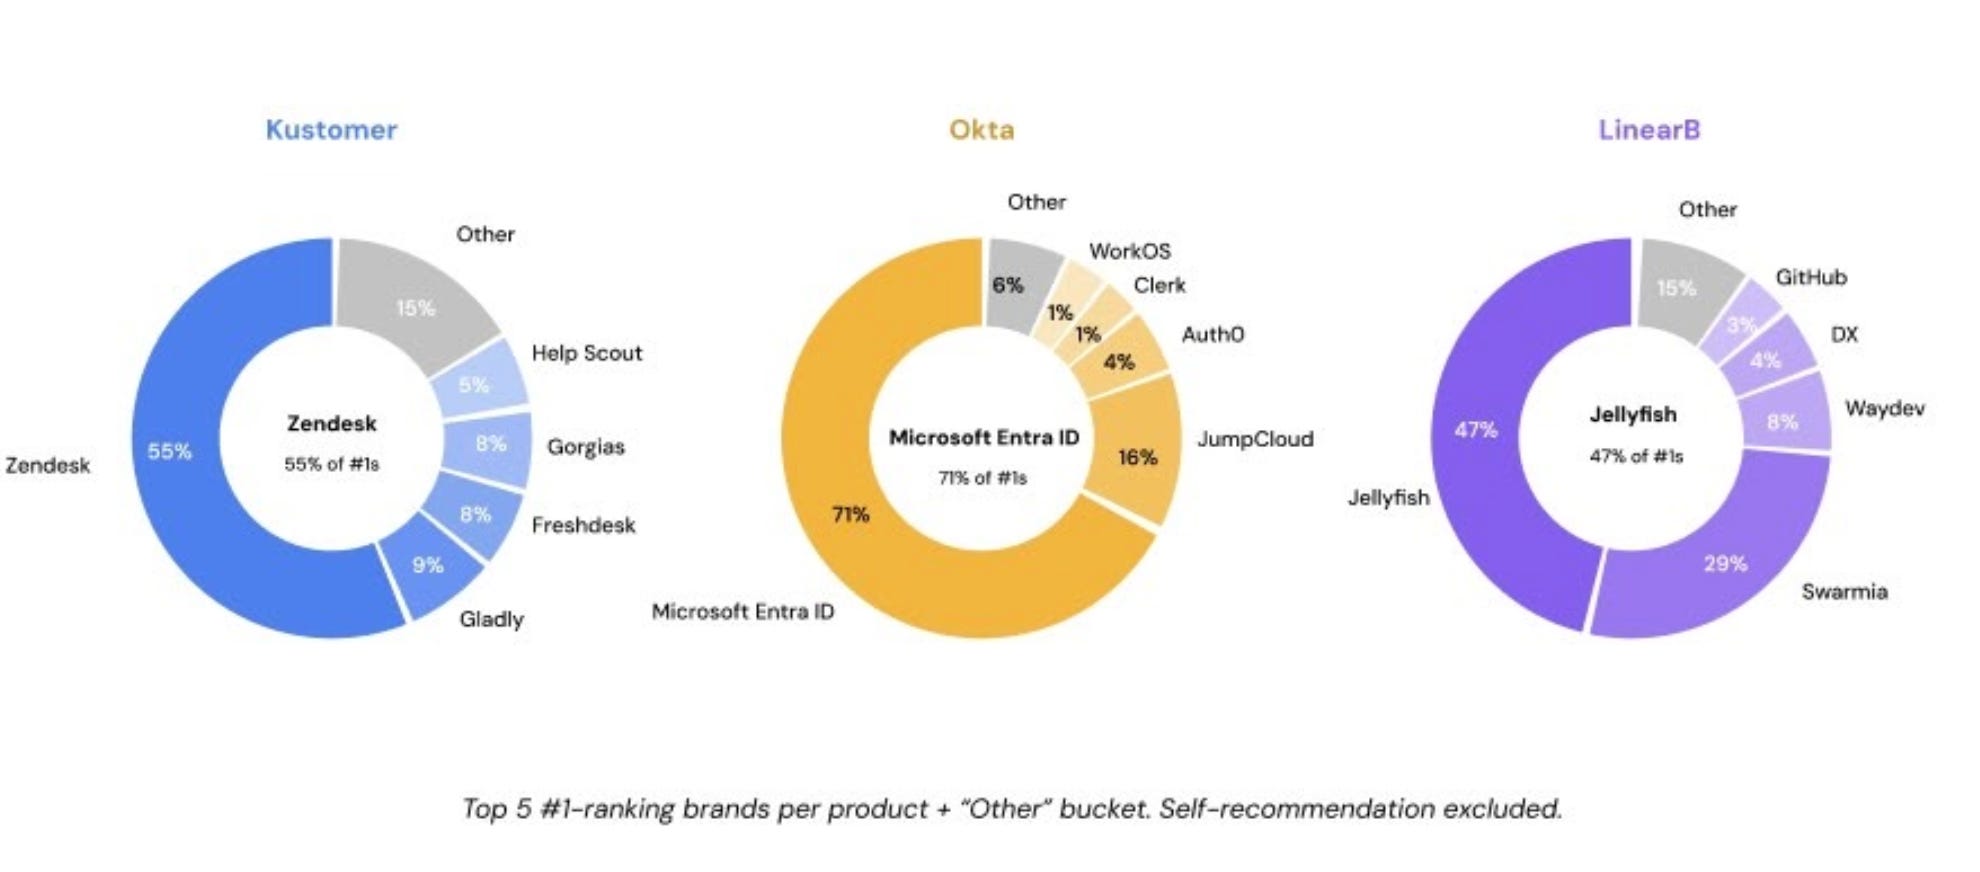
The concentration sharpens at the top spot:
Microsoft Entra ID took #1 in 71% of Okta alternatives queries.
Zendesk took #1 in 55% of Kustomer alternatives queries.
My thesis is that AI search has a category awareness layer that brands either live inside, or get excluded from.
Once a category arrives at a consensus pool of 4-5 brands, challengers can’t bulldoze their way into AI answer recommendations with GEO hacks.
The pool has already been decided by the accumulated signal infrastructure consisting of years of reviews, listicles, analyst coverage, comparison content, and organic authority that cements a deserving brand.
AI search tools are simply retrieving from that digital infrastructure.
What this means for your GEO strategy:
You need to find out which side of the category consolidation you fall on. And the answer you get determines your next move.
If your brand is inside the pool: the work is defense and narrative control. Continue the accumulation of the brand signals that put you there in the first place. Refine your competitive positioning and monitor for sentiment.
If your brand is outside the pool: you need 3rd party corroboration that is aligned to the category. AI search has already decided what to recommend. The work is building the underlying category infrastructure (the reviews, the analyst relationships, the comparison content, the earned mentions across the citation ecosystem).
Neither of those is a channel-optimization problem. Both are category-positioning problems, and they belong on the CMO’s strategic priority list.
Mistake 2: Expecting the same brand mention rate across ChatGPT, Gemini, and Perplexity
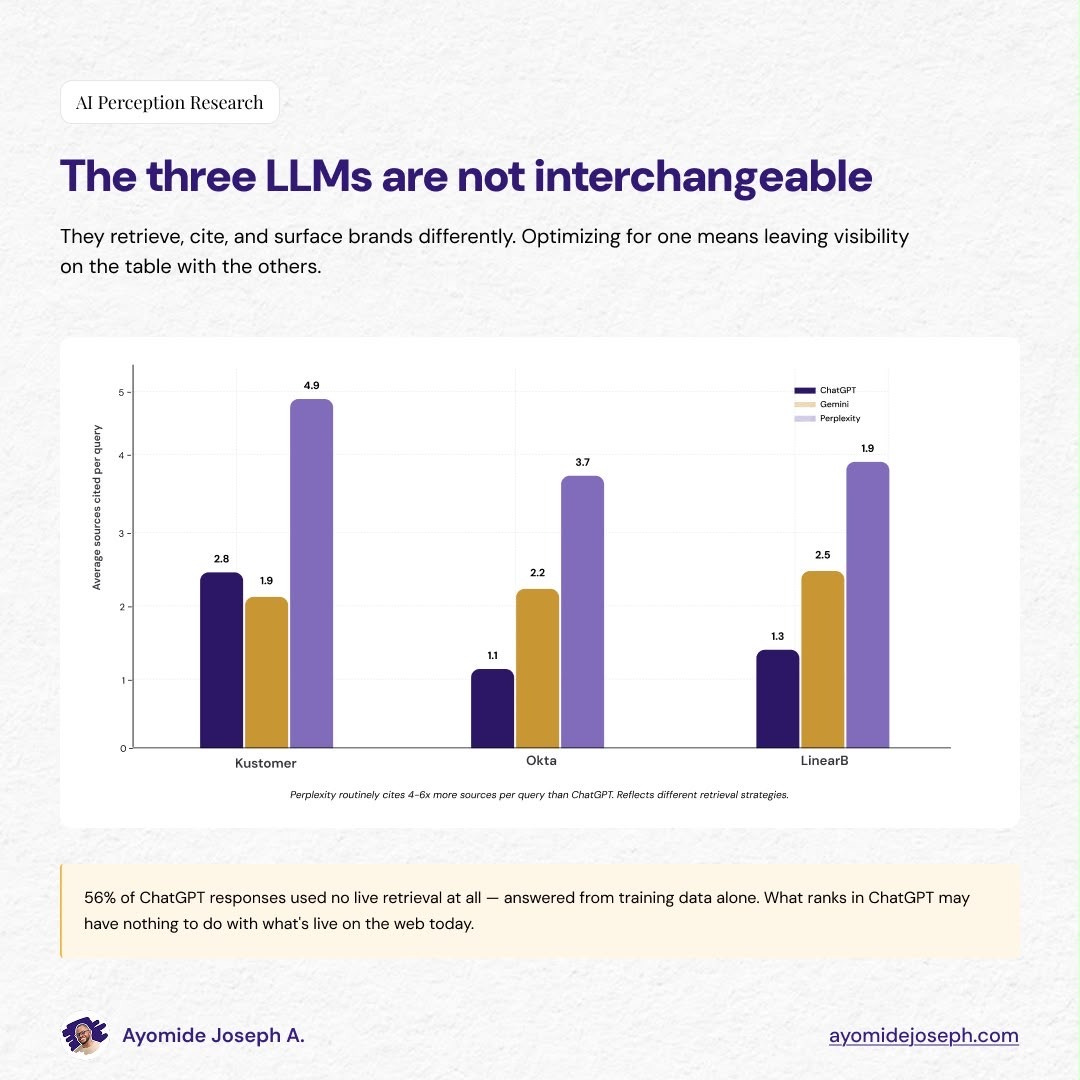
What we learned about retrieval behavior
ChatGPT searched the live web on only 44% of the 270 queries — versus 56% were answered from its training data alone, with no fresh retrieval step.
Gemini searched the web 74% of the time.
Perplexity searched the web 100% of the time.
ChatGPT relies more on its own training data to build answer summaries, which means it might be referencing outdated information about your brand.
Meanwhile, Gemini and Perplexity are more likely to be working from fresh reads of the current web since they rely more on search grounding.
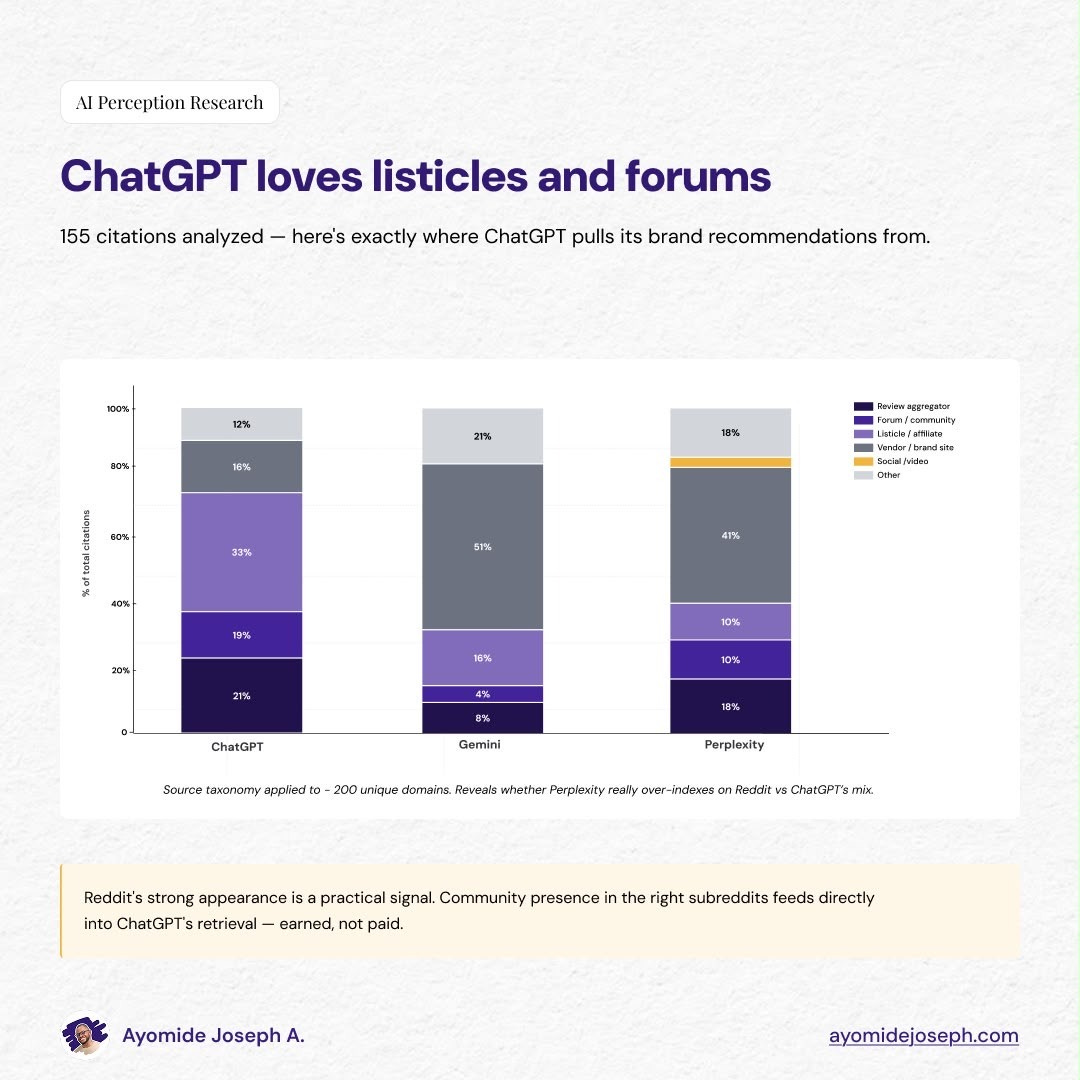
The source mix diverges across AI search platforms
About a third of ChatGPT’s citations came from listicles, i.e., the “best X alternatives” articles that have been the workhorse of B2B content marketing for a decade. A smaller chunk came from forums, almost all Reddit.
Gemini, by contrast, pulled more than half its citations from vendor websites: company blogs, comparison pages, product docs.
Perplexity mixed vendor pages with original sources like analyst content and product documentation, at a citation density three to four times higher than ChatGPT.
What this means for your GEO strategy:
You need a source strategy, not just a content strategy.
Your owned website content is the foundation pillar for GEO. The rest of the work happens across the places AI systems use to validate category authority:
Review platforms
Analyst sites
Third-party listicles
Reddit and community discussions
Competitor comparison pages
Partner and integration marketplaces
Product documentation
Customer case studies
YouTube and podcast mentions
Industry publications
Kevin Indig says AI favors entities it already recognizes 💡
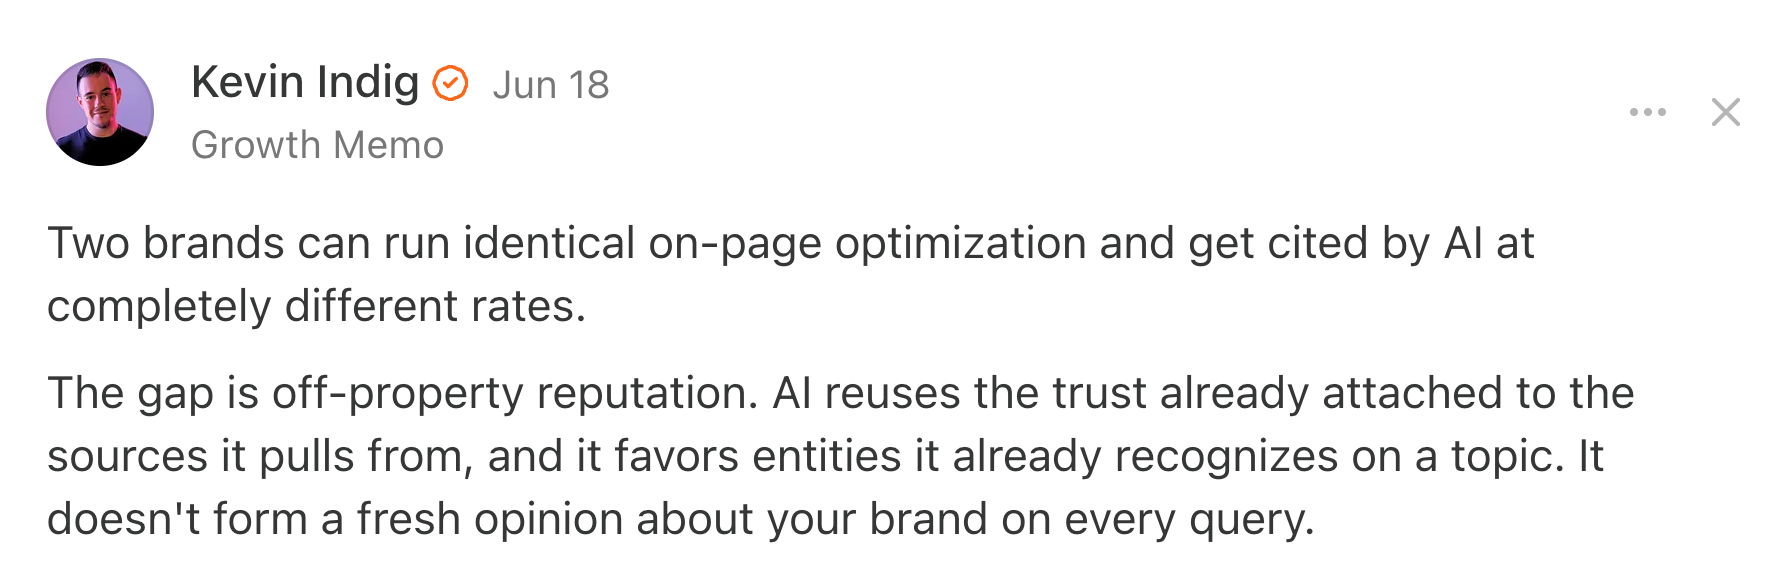
The real work is making sure credible sources consistently describe your brand in the right category, against the right competitors, for the right use cases. AI search tools are looking for corroboration on your brand.
So instead of asking: “Why are we not showing up in ChatGPT?”
You should ask:
Is our messaging aligned to the right category?
Does the website make our category alignment obvious?
Do we have a BOFU content strategy aligned with our category pain points
Do we have an external authority gap?
Which sources are being cited?
Are we present in the sources each platform trusts?
Which competitors are being cited instead of our brand?
Do third-party sources like reviews and analysts validate our brand story?
The winning GEO strategy is not tunnel visioned on one LLM.
It’s building a source ecosystem strong enough that no matter where the buyer asks the question, the market already has enough evidence to include you in the answer.
Mistake 3: Underestimating the strength of existing category incumbents
The category incumbents get an unfair compounding advantage in AI search.
The brands that build the strongest signal infrastructure over 12-18 months in a contested category tend to become the ones that LLMs converge on. Once that consolidation happens, the cost of displacing the winners gets too expensive to overcome.
For reference, Zendesk comes up as a top “Kustomer Alternative” across all LLMs—i.e., the category has consolidated. For a new and existing brand outside that pool to even show up, they’d likely need 18 months of consistent work.
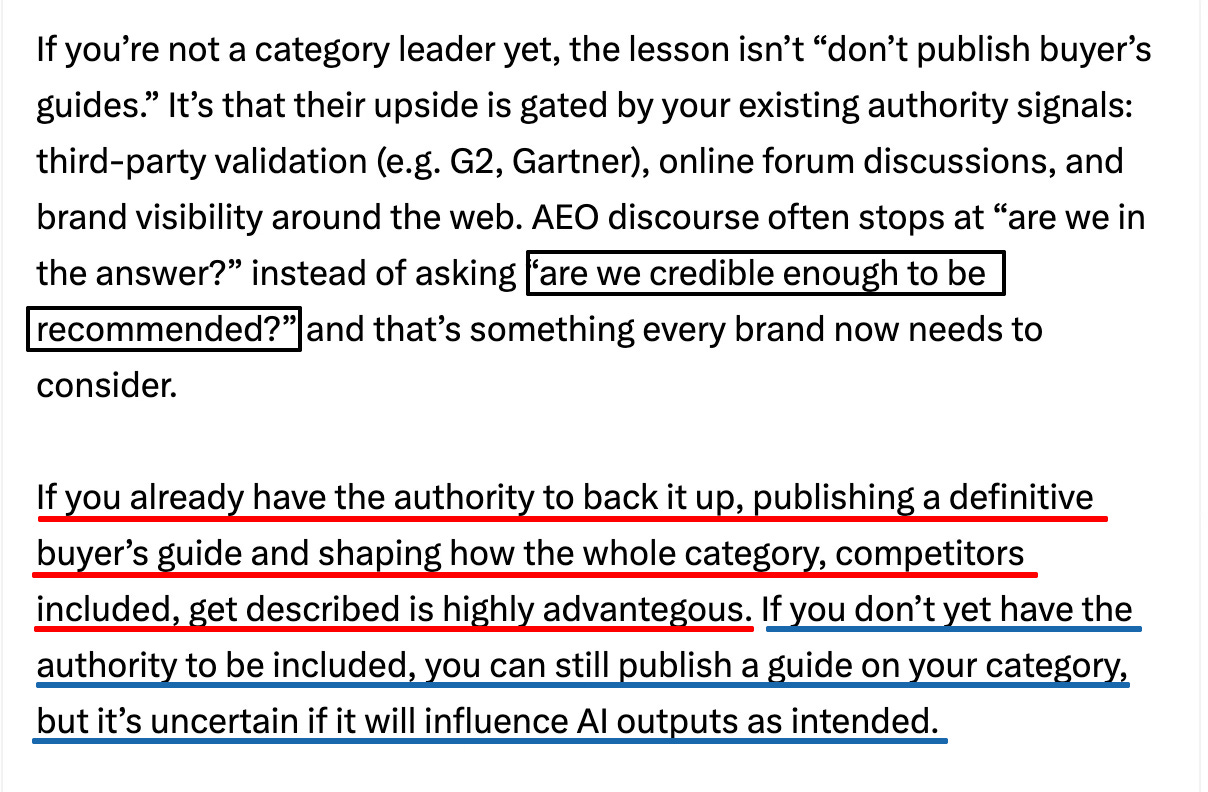
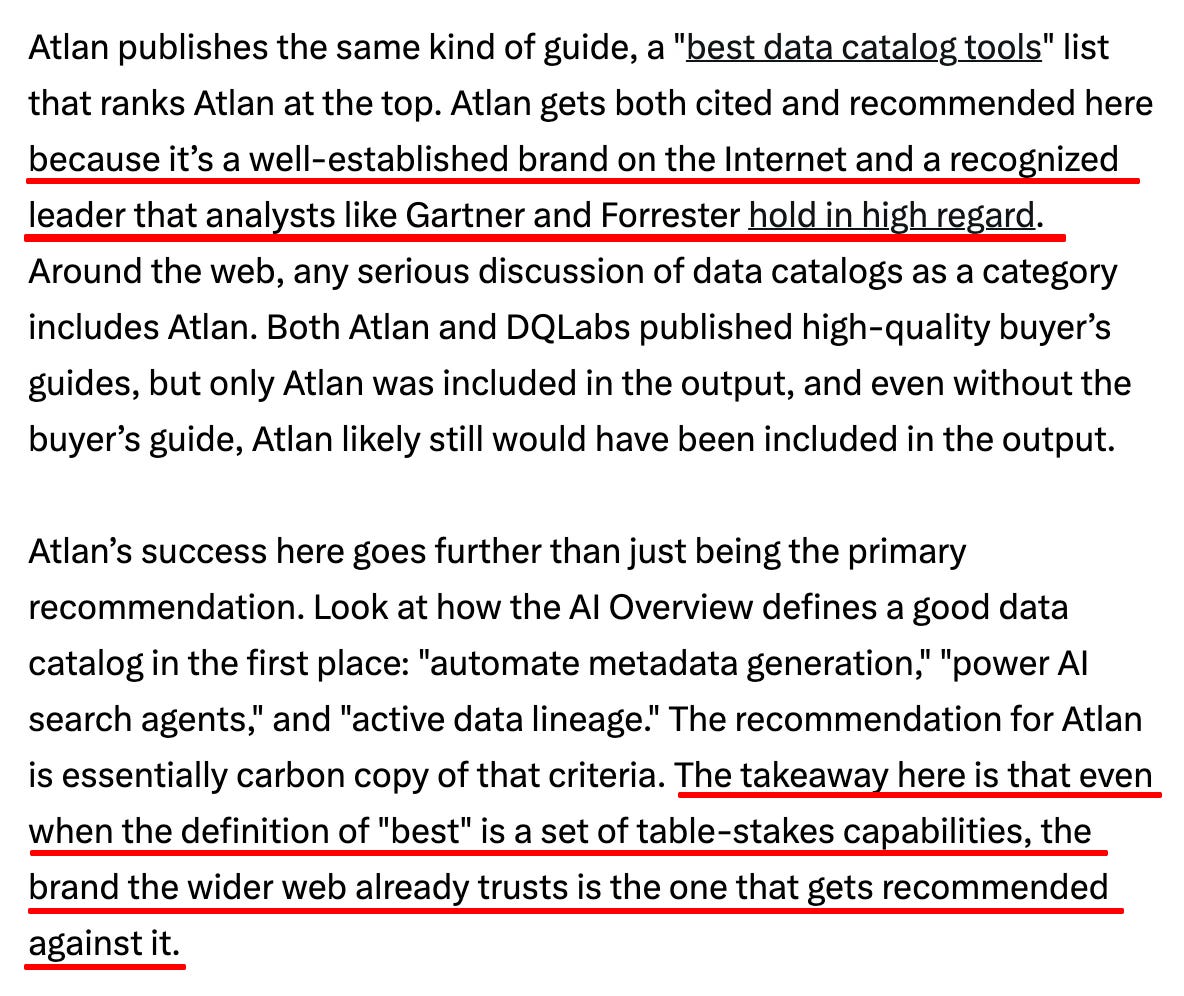
John-Henry Scherck made a similar observation recently on X of two companies running identical buyer’s guide strategies.
One failed, and one succeeded. But why? Because buyer’s guides have limited ROI if your brand is lacking category-level 3rd party corroboration.
What this means for your GEO strategy:
Timing shapes what’s actually achievable. The GEO investments that produce results inside a 6-month window are different from the ones that require 18-24 months to compound, and misreading the timing can be costly.
The 6-month investments should revolve around partnership building and first party content strategy. This involves making sure your product pages, landing pages, comparison content, features and solutions are aligned to the proper category. From there, find ways to get included on third-party listicles AI engines cite, analyst briefings that produce recognition, comparison content on high-authority sites where you’re currently missing, etc.
The 18-24 month investments are the ones that compound: Original research programs, review aggregator depth (G2, Capterra), Reddit and community presence built through genuine participation, and category-defining content that becomes canonical over time. These don’t produce quarterly visibility movement, but they’re the layer that determines which brands the LLMs converge on when the category consolidates.
You can read and download the full report here: Query Fan Out Experiment: How ChatGPT, Gemini, and Perplexity Recommend B2B Alternatives Across 270 Naturalistic Queries
Mistake #1 is spot on. It’s something you have to build and earn across every door AI opens. Optimization can and should be done, but if you haven’t built the external world to validate it… AI search will find someone else that did.
I think this may be particularly true in e-commerce. The safe bet for an AI buying agent is a major brand.